It almost feels as if the economic data is being coerced into creating a neatly oscillating narrative for the US economy to feed Wall Street’s volatility hungry quant trading strategies and derivative writing institutions.
I don’t promulgate such an idea as a tin hat conspiracy theory; instead it is born of an understanding that, as an investor, one is only correct when the market agrees with you, and what better way to make markets agree with you than control the narrative. After all, who is it that we look to when we desire an explanation of the markets – it’s the investors. I hope that circularity is clear.
President Trump’s exceptional profits during his second term in office could be a barometer for this dynamic – he is a volatile character after all, or maybe that was instead achieved primarily by utilising his additional powers of political persuasion and the access to non-public information that comes with it, for which he is increasingly being criticised.
This week’s pivot on the outlook is served up by the nonfarm payroll labour market data which today reported an addition of 162,000 jobs far ahead of an expected 55,000 and a much more positive number after two months of large downside surprises.
One would hope for a bit more optimism following weeks in which bond yields have been rising in the face of higher energy prices and concerns over spiralling government debt. Alas, for the bond markets this is no silver bullet. Instead, a resilient labour market gives the Federal Reserve less reason to be dovish and keep interest rates low and thus bond yields are expected to remain higher.
While the dollar looks set to benefit, equity markets are equally unenthused by the possibility of higher interest rates and thus Thursday’s recovery is losing steam into the weekend. This data is quickly being tarnished with the ‘good news is bad news’ brush.
In addition, having been criticised by key leading investment leaders such as Stan Druckenmiller and Mohammed El-Erian for moving beyond informing and influencing market outcomes to attempting to impose market outcomes, the US Treasury and the administration is beginning to flounder confidence.
Today, in a Truth Social post, Trump has demanded that the Federal Reserve slash interest rates by threat of cutting off trade with countries with which the US maintains a trade deficit. Thankfully the midterms are drawing near otherwise this would feel like we are heading for a repeat of April-2025’s Liberation Day.
With key global central bank interest rate decisions aplenty in September, it could prove to be a volatile month, and the Bank of Japan should be of keen focus after two officials hinted at the possibility of a faster pace of rate hikes having previously restricted themselves to one hike every six months.
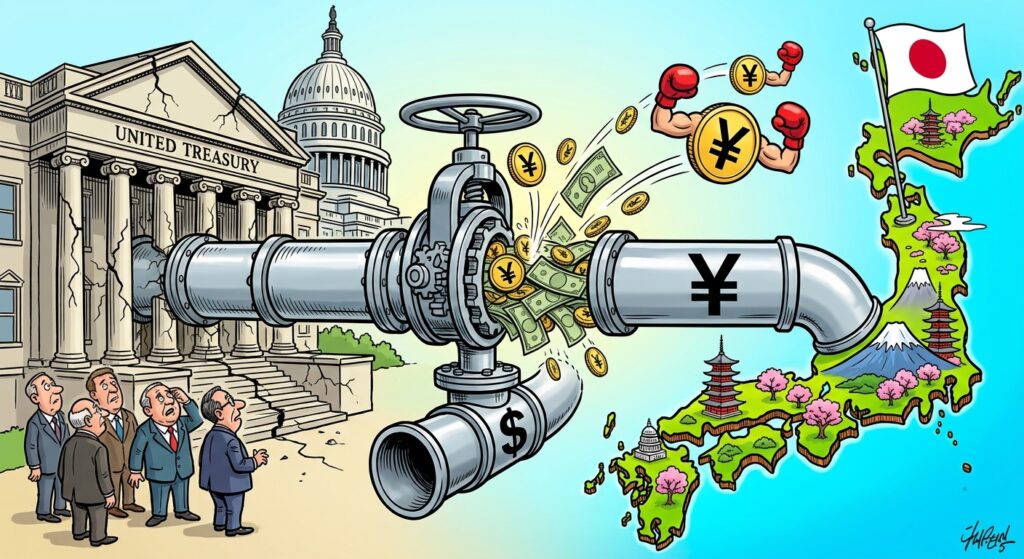
This is crucial for the Japanese Yen which has strengthened considerably in recent weeks but still finds itself on the wrong side of a Yen-Dollar carry trade owing to bond yield differentials of near 2%. The huge amount of leverage which bolsters US asset prices that is derived from this circumstance could be reduced to nothing in as little as a couple of years as a result, not to mention the potential repatriation of c. $1tn of Treasury investments.
For those of you who read regularly, these themes are nothing new, but maybe we are closing in on an event that shakes things up a bit, and hopefully an opportunity to add some value.
Where are markets up to?
The rolling 12 month % cumulative returns in local currency from various indices is shown in the following chart:

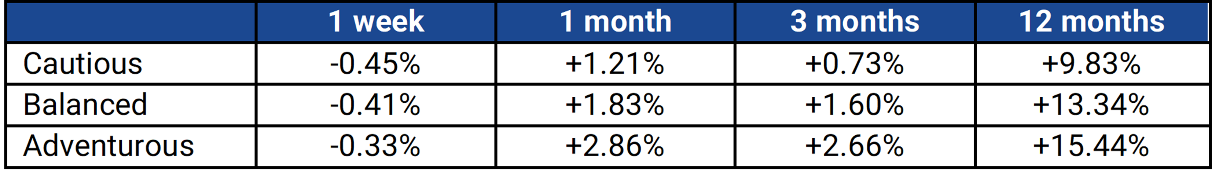
Where are the portfolios up to?
The portfolio performance, net of fees, to close of business on Thursday is as follows:
As ever, if you would like to discuss any aspect of your portfolio, please do not hesitate to contact us on service@blythefinancial.com.