In the aftermath of Federal Reserve Chair Kevin Warsh’s hawkish Jackson Hole speech and last week’s strong employment figures, we were expecting the week to centre around a tense buildup to today’s US inflation data print.
Instead, the ratcheting up of crude oil prices as the US-Iran war drags on with no sign of a treaty, and the subsequent knock-on impact that has on inflation, has renewed upward momentum in bond yields ahead of that data.
It became clear that overall OPEC production fell by 640,000 barrels per day in August, but that was secondary to the issue of transit as threat levels in the Red Sea intensified after Houthi rebels seized control of the strategic Yemeni port city of Mocha.
But crude oil is only half the story; the actual cost hitting the real economy is also determined by its derived refined products. Crack spreads, which are a measure of the margin paid for refining, took a significant second leg up in July and have remained stubbornly high since. What’s changed this week is that central banks are increasingly monitoring this data as a forward guide on inflation.
For Europe, higher energy prices threaten a deeper manufacturing contraction while the European Central Bank has also tightened monetary conditions by raising interest rates to 2.5%. Christine Lagarde followed in the footsteps of Fed Chair Warsh by giving limited forward guidance.
For now, the price action has mostly been contained to bond markets with equities slightly lower but somewhat sanguine. The Fed and the Bank of England are due to make their respective interest rate decisions next week, but it is the Bank of Japan which has the potential to rile markets.
While an interest rate hike is now priced in after recent comments from its officials, a particularly aggressive hawkish outlook could sharply reverse carry trade induced equity market leverage. Conversely, there has been little pullback for the Yen since it strengthened on those comments, so a relatively benign outlook could reengage upward momentum in US equity markets.
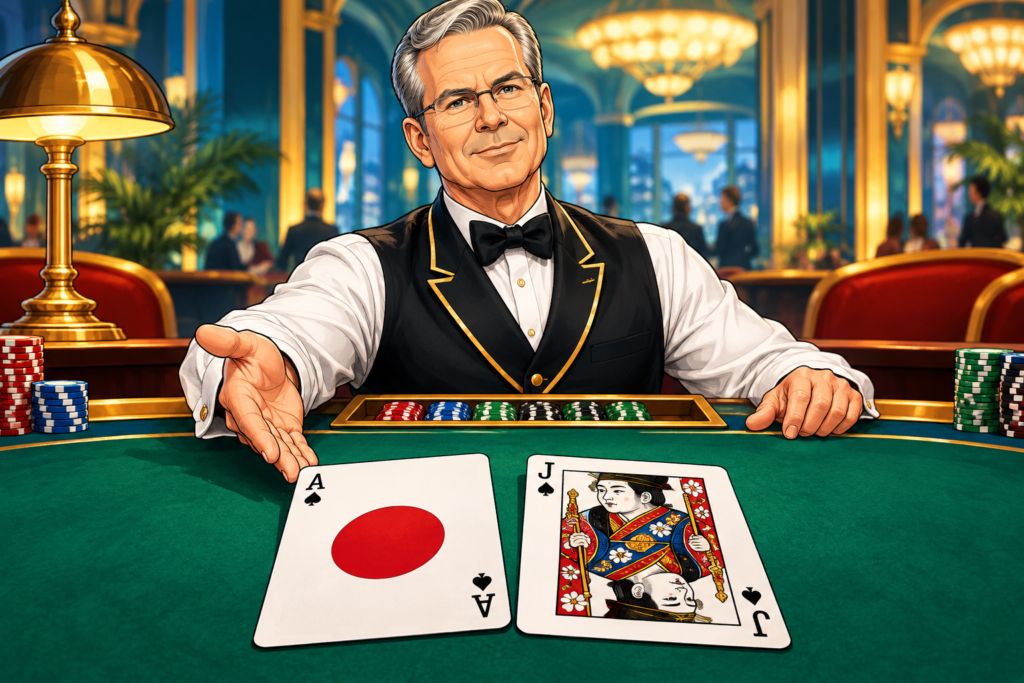
Treasury Secretary Scott Bessent also stepped in to tame this dynamic by warning currency speculators that he has asymmetric information and insight into the policy path for the Bank of Japan and describing himself as “the house,” challenging investors to “bet against me if you want to”.
Thirty-two years ago, he himself would have been on the other side of these circumstances, having helped George Soros ‘break’ the Bank of England by betting against the pound, and just thirteen years ago he was also betting against the yen.
While batting for Japan in this instance, his comment didn’t traverse the Pacific routinely, with the literal translation of ‘house’ reportedly having connotations of shadowy underground figures operating illicit gambling rings, initially appearing as some form of geopolitical muscle flexing.
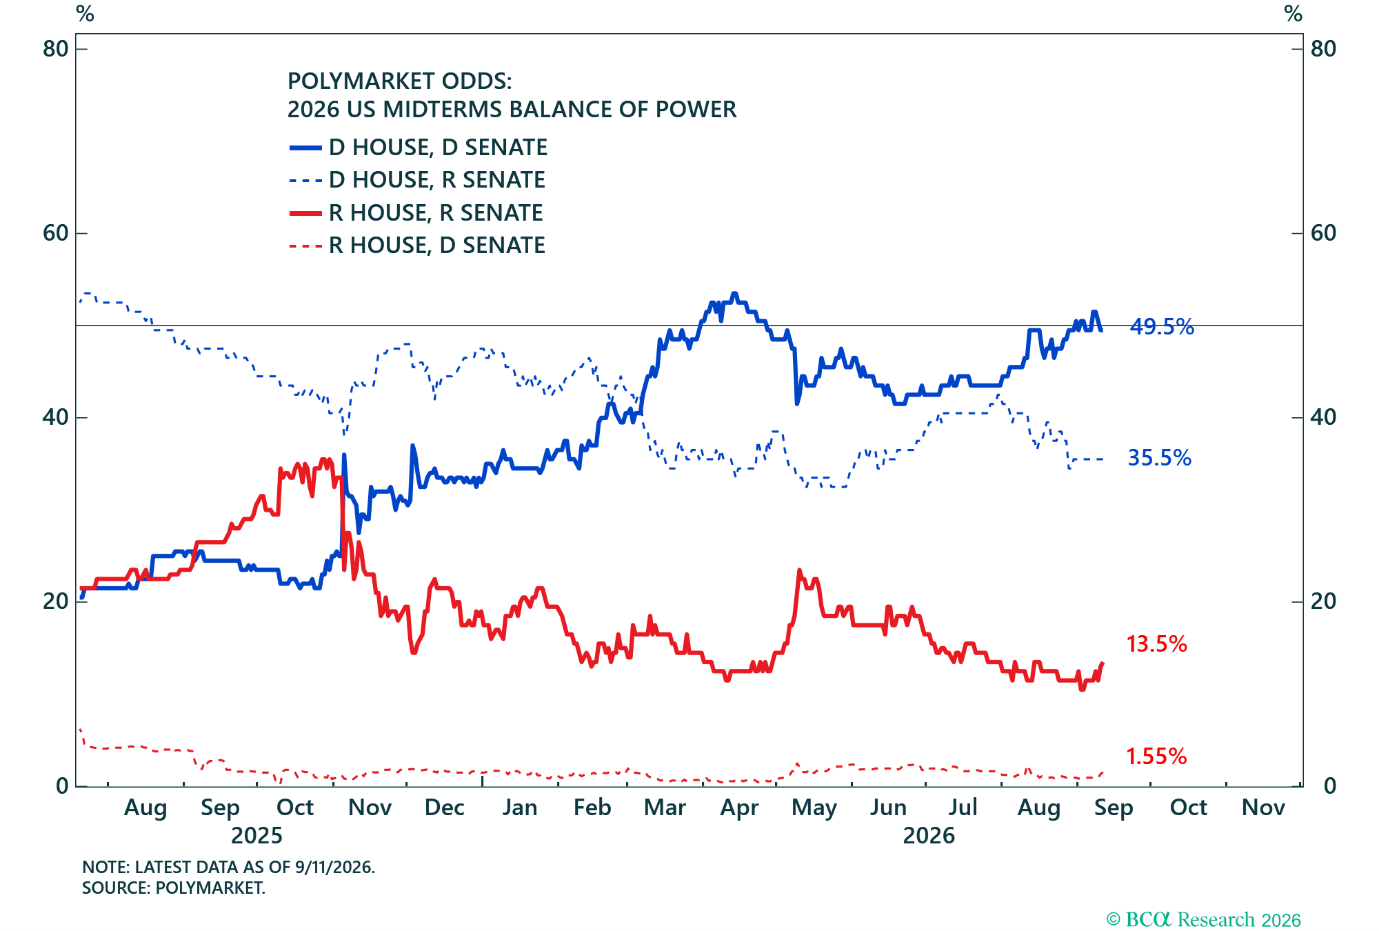
Having navigated the BoJ meeting, markets will likely turn their attention back to the US mid-term elections. The first sign of President Trump’s assistance to the Republican campaign is an offer of $5,000 to all citizens should the GOP retain control of both the Senate and the House of Representatives.
This was taken with hefty pinch of salt, not only because he has made promise of these types of payouts previously, only to have them blocked by Congress or for his tariff revenue to be stymied by the Supreme Court, but also because there is simply a very low expectation of that outcome under current polling (1.55%):
Canadian tariffs on US goods come into effect this week – these, however, will not be undone by any judicial legislator.
China exports by Region
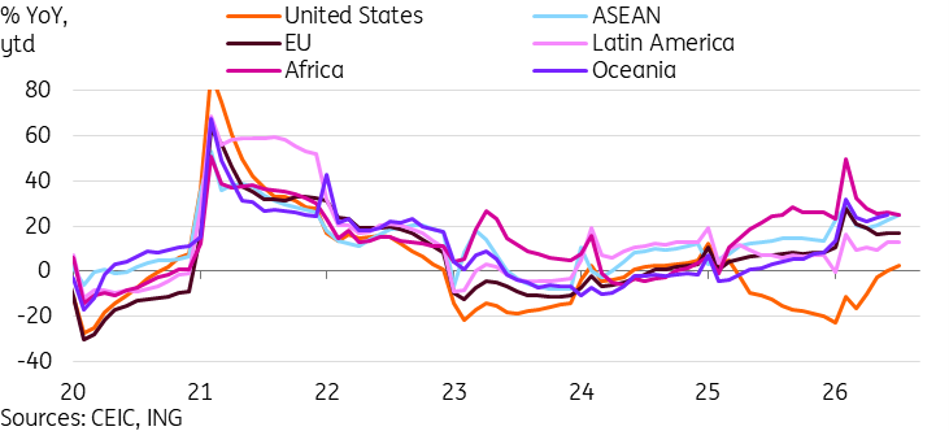
Chinese exports to the US have rebounded to pre-Liberation Day levels so it is increasingly looking like Trump’s legacy will be the consequences of the Iran war, unless he can somehow bring about a turnaround of mid-term election fortunes.
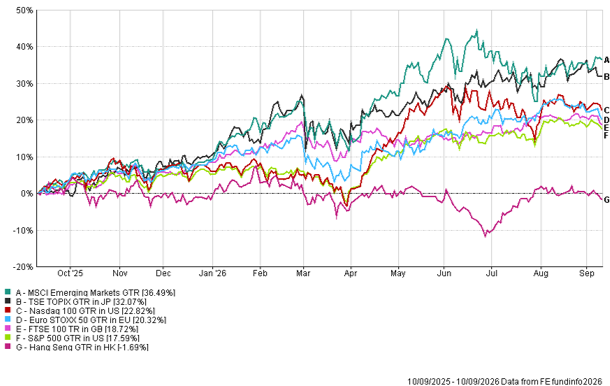
Where are markets up to?
The rolling 12 month % cumulative returns in local currency from various indices is shown in the following chart:
Where are the portfolios up to?
The portfolio performance, net of fees, to close of business on Thursday is as follows:

As ever, if you would like to discuss any aspect of your portfolio, please do not hesitate to contact us on service@blythefinancial.com.